Category Archives: Bookkeeping

Top Bookkeeping Services in New York 2025

tax and bookkeeping New York

We pride ourselves on filing all related financial documents on time and keeping you updated every step of the way. The two main types are double-entry bookkeeping, where every transaction affects two accounts, and single-entry bookkeeping, a simpler method for small businesses. Free up time in your firm all year by contracting monthly bookkeeping tasks to our platform.

New York City CPAs That Deliver Results
tax and bookkeeping New York

With trial balance advancements in technology, many businesses are shifting to online bookkeeping services. These cloud-based solutions offer real-time access to financial data, automated reporting, and seamless collaboration with accountants. Small businesses need bookkeeping services to ensure accurate and up-to-date financial records. This is essential for making informed business decisions, preparing tax returns, and meeting financial reporting requirements.
tax and bookkeeping New York

Stop wasting away wealth on unnecessary taxes. Speak to an expert Tax Consultant Today

Outsourcing bookkeeping services is an efficient way to manage financial records without the burden of hiring a full-time employee. Many businesses in New York rely on outsourced professionals to handle payroll, invoicing, reconciliation, https://www.bookstime.com/ and financial reporting. In the fast-paced business environment of New York, accurate and reliable bookkeeping services are essential for companies of all sizes. With an increasing number of businesses opting for outsourced and remote bookkeeping, finding the right service provider has become a priority. Miller Company LLP’s international tax experts have over 25 years of accounting and consulting experience. We understand your unique small or large business obstacles and objectives and can develop a personalized solution that meets your accounting, compliance, and tax needs.

Get In Touch With Commerce CPA, LLC
tax and bookkeeping New York

Anil and our team at 212tax constantly seek out the latest changes to reduce taxes. Not only do you keep more of your income, we show you how to make your wealth grow faster. Businesses must actively elect to participate in this tax structure each year. This voluntary nature allows businesses to assess whether PTET is beneficial for their unique circumstances. Your small business answering service can filter calls and pass the best opportunities directly to your sales and support team.

  • We work tirelessly to ensure that you are financially healthy, making us true partners in your growth and success.
  • Under PTET, taxes are paid by the business rather than the individual members or partners, ensuring full deductible on federal returns.
  • We provide clear and easy-to-understand reports and documents that make filing your taxes a breeze.
  • Whether you need small business bookkeeping, online financial management, or outsourced bookkeeping solutions, choosing the right provider is crucial for your company’s financial success.
  • Outsourcing this service reduces errors and improves financial transparency.
  • Work with experienced, best rated tax accountants in NYC who create those desired outcomes.
  • Some entities may incur higher administrative or accounting costs due to the need for professional tax assistance.
  • You can trust that your financial statements accurately reflect your business’s financial status.
  • Best Pro Bookkeeping & Tax Services has proven to be the best bookkeeping service company in New York, offering tailored solutions, expertise, and outstanding customer service.
  • Totally invested in your success, they work with your business as if it were their own.
  • Our bookkeepers can also assist in setting up and training your staff on the financial systems that you might be using or installing, such as QuickBooks or other legacy systems.
  • When your top NYC CPA at Miller & Company gets to know you, you can expect nothing less than life-altering scenarios.

Tax accounting isn’t just numbers on a page; it impacts your life in fundamental ways. Without constant vigilance, your financial, tax accountability can spiral out of control. CPA Firm in NYC Miller & Company of New York bookkeepers in new york finds solutions that let your wealth work for you, not against you. Tax laws don’t stop changing and neither do we — we have over 20 years of experience and stay current on the latest developments and best practices. Individuals — we excel in complex tax situations such as RSUs, ISOs, flow-through investments, real estate, multi-state issues, foreign income, and many more.

  • Our team has worked with countless clients across a wide variety of industries, providing top-tier CPA services to meet their unique financial needs.
  • Let us handle the details while you focus on what you do best – growing your business.
  • With an increasing number of businesses opting for outsourced and remote bookkeeping, finding the right service provider has become a priority.
  • The Valkyrie Accounting team is dedicated to staying up-to-date on all regulatory and legislative developments, both locally and nationally.
  • Tasks include reviewing spending in marriage or reallocating capital and ownership when adding a new business partner.
tax and bookkeeping New York

You’ll have direct access to your bookkeeper and can schedule regular check-ins to review your business’s financial health. Say goodbye to bookkeeping frustrations and hello to efficiency with Tax & Accounting Hub by your side. As a valued client, you get a secure, password-protected portal to store and access your important financial documents from anywhere at any time. Creative advice and outstanding performance — merged with relentless dedication and vigilant customer service — mean that your CPA responds quickly to requests and questions. Get training and ongoing support from our best rated QuickBooks ProAdvisor that offer committed personalized service.
tax and bookkeeping New York

In today’s fast-paced business world, maintaining accurate financial records is crucial for any company. We use secure, encrypted systems to manage and store your financial data. Tax & Accounting Hub firm ensures that your information is protected at all times, maintaining confidentiality and privacy in every transaction.

Organize Your Books with New York City’s Best Bookkeepers

  • Whether you need an accountant, comprehensive financial management, or expert business and personal tax preparation solutions, we’re here to support your business.
  • Entities with nonresident members must consider how the tax credit will be applied in their home states, which may not recognize the PTET credit.
  • This can lead to potential double taxation or additional administrative burdens.
  • In today’s fast-paced business world, maintaining accurate financial records is crucial for any company.
  • We manage your monthly bookkeeping efficiently with QuickBooks, guaranteeing precise and error-free transactions that translate into significant cost savings for your business.

Bookkeeping is the systematic recording of financial transactions to ensure accurate financial statements. We strive to take over the essential accounting needs of your law firm so you can spend more time working billable hours and bring in higher revenues. Our proactive tax planning strategies leverage every deduction, break, and incentive available to save you money. With 10+ years of experience, we offer bookkeeping, payroll, AP, AR, and bank reconciliations for businesses of all sizes. Tax season can be overwhelming for individuals and businesses alike. We offer flexible communication options, including phone, email, and video calls, to keep you in the loop.
What Does Pro Rata Mean? Definition, Calculation & Examples

Withdrawals will consist of 20% taxable and 80% non-taxable money as a result. David is comprehensively experienced in many facets of financial and legal research and publishing. As an Investopedia fact checker since 2020, he has validated over 1,100 articles on a wide range of financial and investment topics. Ethical considerations should guide pro rata decisions to maintain trust and equity among participants.

AccountingTools

Pro rata in the insurance industry is used to determine the amount of premium due for a policy that only covers a partial term. By following these steps, you can harness the power of spreadsheet software to perform pro rata calculations efficiently and accurately. Spreadsheets provide flexibility and control, making them a valuable tool for various pro rata scenarios in your professional and personal endeavors.

Settlement Among Multiple Insurers

The revenues of an what is a pro rata distribution asset sale made by a bankrupt firm are allocated among shareholders according to their percentage of ownership. This prevents discrimination against minority shareholders during liquidation payouts. The shares are allocated in the ratio of shares applied for to total shares applied under each category of investors.

  • One common method is “pro rata,” which ensures fair allocation based on time, usage, or shared responsibility.
  • It ensures that each shareholder receives an amount proportional to their shareholding.
  • This method is widely accepted and commonly used in business, finance, and government.
  • Equal division is particularly useful when you want to distribute resources without any bias, giving everyone an equal slice of the pie.
  • The pro-rata formula is a critical concept to understand in various fields.
  • This ensures each investor shares proportionately in the ups and downs of the investment based on their ownership percentage.

The principle of pro rata is applied when resources, time, or money need to be allocated fairly across different parties. When a company generates profits, it may decide to share those earnings with its shareholders. Pro rata calculations ensure that each shareholder receives a fair and proportionate share of the dividends. It becomes useful for organizations in the context of expenses, income splits, and other monetary transactions where somebody pays or receives money from somebody or some company. In order to be precise and fair in the appraisal, businesses employ this concept in the analysis and allocation of finance figures.

  • A high frequency of bonus issues sometimes indicates suboptimal capital allocation by the company.
  • There are 365 days in the year, and there are 226 days between January 1st and August 15th.
  • This simple formula is adapted and applied in different situations in the stock market.
  • Pro-rata distribution is a critical principle that governs the allocation of resources in many different contexts.

In this article, you will mainly learn about what is pro rata in business and how to calculate pro rata distribution using the formula. You will also learn about the ways in which pro rata works for businesses and how this formula helps in distributing reimbursements for participation. Finally, we will share with you the major uses of the pro rata distribution formula. In estate planning specifically, the term “pro rata” indicates how an estate’s assets should be divided and distributed among the decedent’s beneficiaries.

Unlike other distribution methods, such as a discretionary distribution, pro rata distribution is based on a clear and objective formula that ensures that everyone receives a fair share. This can help to reduce the potential for disputes or misunderstandings among shareholders or investors, which can save time and money in the long run. The pro rata formula is a relatively simple concept, but it can become complex when applied in different scenarios.

Adjusting insurance premiums balances risk assessment with financial responsibility. Premium amounts depend on factors like age, location, and claims history, which insurers evaluate using statistical models. For instance, a driver with a history of accidents may face higher premiums due to increased risk.

By following these steps, you can easily calculate the pro rata distribution for any situation. Depending on the situation, pro rata distribution can have different outcomes. For example, if a company is distributing its assets to shareholders, pro rata distribution may result in some shareholders receiving a larger share than others, depending on their investment. However, in some cases, pro rata distribution may result in each investor receiving an equal share. When it comes to distributing assets or funds, pro rata distribution takes into account the total value of the assets or funds, not just the monetary value.

Understanding Pro Rata

A pro rata payment is a payment made out to an individual utilizing the pro rata calculation. The amount you receive is typically proportionate to what you’re entitled. Pro rata is a term derived from Latin that essentially means “proportionate.” The term is used to describe a proportionate allocation or distribution of something, such as an asset or capital payout. Learn how pro rata applies in insurance, from premium distribution to cancellations and reinsurance, ensuring fair cost allocation among insurers and policyholders. Pro rata calculations rely on fundamental components that ensure equitable distribution. Understanding these elements allows individuals and organizations to apply proportionate allocations accurately.

You can then apply the ratio to any related item to find the same proportion. Do you have any more to add regarding the application of the pro rata system? You could argue that pro rata is the term describing the concept, while prorated is the resulting number that was calculated using this concept. Disputes can arise when policies contain differing “other insurance” clauses.

Pro Rata: Definition, Uses, And How To Calculate It?

The total amount represents the aggregate sum to be allocated, forming the basis for distribution. In finance, this could relate to dividends distributed by a corporation or the total cost of a shared expense. For example, if a company is distributing a $100,000 profit pool among shareholders, knowing the total amount ensures clarity on the size of the pool.

Pro rata distribution is used when a company is distributing its assets to its shareholders. Each shareholder will receive a portion of the assets based on their ownership percentage. Pro rata distribution can help to prevent insider trading or other forms of market manipulation. If something is given out to people on a pro rata basis, it means assigning an amount to one person according to their share of the whole. While a pro rata calculation can be used to determine the appropriate portions of any given whole, it is often used in business finance.

Actuarial science helps quantify these risks, ensuring premiums are competitive while covering potential claims. Pro rata can be communicated as a percentage like a shareholder who owns a 10% share of the company’s stock. It can also be expressed as a quantity, such as the shareholder who owns 100,000 of the company’s one million shares. In situations where pro rata decisions have ethical implications, it’s vital to prioritize fairness and transparency. Let’s start with some concrete pro rata examples to illustrate how these calculations work in different situations. Alfred invested more money when they started the business so he has a bigger share than Eliza.

Understanding pro-rata calculations is vital as it upholds the core principle of allocating benefits or obligations based on ownership percentage. The simplicity of pro-rata formulas masks the complexity involved, yet employing them ensures proportionality, transparency and fairness, which minimizes disputes. The pro rata principle is also applied in the context of dividend distribution. Companies often pay dividends to their shareholders as a reward for their investment. These dividend payments are distributed on a pro rata basis, which means each shareholder receives a proportionate share of the total dividend amount, based on their percentage ownership in the company. The pro rata principle ensures fairness and equitable distribution, making it an essential concept in various industries and scenarios.

We will provide you with practical examples, essential formulas, and solutions for various pro rata challenges. Real estate management frequently relies on pro rata calculations for equitable distribution of costs and expenses among tenants or property owners. While pro rata distribution is a commonly used method for distributing resources, it may not always be the best option.

Allocating the appropriate portion of an annual interest rate to a shorter time frame can also be done via pro rata. Because you won 4% of the shares, you are entitled to 4% of the dividend payment. Examples of pro rata being used include the division of a loan payment being adjusted monthly. The total amount paid by the borrower against the loan is the same each month. However, the amount of monthly payments that are allocated between the principal payment and the interest paid for the loan change each month as the loan is progressively paid off.

Pro Rata in Insurance Claims

Weighted pro rata allocation takes into account varying degrees of importance or value among participants. It assigns different weights to each participant, affecting their share of the allocated resources. This method is ideal when participants have different levels of significance or influence in a given context. Percentage-based allocation is a versatile pro rata method that distributes resources based on predefined percentages.

Straight Line Basis Overview, How To Calculate, Example

However, the rate at which the depreciation is recognized over the life of the asset is dictated by the depreciation method applied. In the realm of accounting and finance, the straight line method is a tool for calculating amortization and depreciation. It’s all about evenly distributing an asset’s costs and value, respectively, over its expected useful lifespan. Accountants use the straight line depreciation method because it is the easiest to compute and can be applied to all long-term assets. However, the straight line method does not accurately reflect the difference in usage of an asset and may not be the most appropriate value calculation method for some depreciable assets.

Depreciation of fixed assets is similar to amortization, and in both, the straight line basis is commonly used to calculate the expense amount. Explore different depreciation methods, seek advice from financial professionals, and consider financial accounting software for improved accuracy. This ensures clearer and more accurate financial reports, setting your business up for long-term success. The term “double-declining balance” is due to this method depreciating an asset twice as fast as the straight-line method of depreciation.

Therefore, depreciation would be higher in periods of high usage and lower in periods of low usage. This method can be used to depreciate assets where variation in usage is an important factor, such as cars based on miles driven or photocopiers on copies made. By the end of the fifth year, the accumulated depreciation would be $45,000, and the book value of the machine would be $55,000. This example illustrates how accumulated depreciation is integral to tracking the value of assets over time and making informed financial decisions. The Straight-Line method is one of the most widely used ways to calculate depreciation. It involves spreading the cost of an asset evenly over its useful life, resulting in the same depreciation expense each year.

Terms

  • From an accounting perspective, the Straight-Line Method is favored for its transparency.
  • According to the straight-line method of depreciation, your wood chipper will depreciate by $2,400 every year.
  • An alternative to straight-line depreciation is the declining balance method, where the value of the asset is reduced by a percentage rather than a fixed amount.
  • Financial statements reflect a clear and predictable pattern of asset value reduction, which can be easily understood by stakeholders, including investors and creditors.
  • This formula subtracts the salvage value (the estimated resale value at the end of its useful life) from the cost of the asset, then divides by the number of years it’s expected to be in use.

After all, the purchase price or initial cost of the asset will determine how much is depreciated each year. This method was created to reflect the consumption pattern of the underlying asset. Deducting the cost of an asset from its salvage value gives us its depreciable amount which in this case is $5000. Dividing it by the annual depreciation expense ($1000) gives us the useful life in years. Depreciation expense in the year of acquiring an asset is the full year’s depreciation expense calculated using the straight line depreciation formula and multiplying that by the time factor. The straight-line method doesn’t account for this accelerated depreciation, resulting in a depreciation expense that doesn’t match the actual decline in value over time.

Because organizations use the straight-line method almost universally, we’ve included a full example of how to account for straight-line depreciation expense for a fixed asset later in this article. Below are three other methods of calculating depreciation expense that are acceptable for organizations to use under US GAAP. Like most businesses, Netflix applies a straight line depreciation schedule to its physical plant, property, and equipment assets. Buildings default to a 30-year span, and furniture and information technology get a three-year life cycle.

Depreciation expense

  • Speaking of predictability, your financial forecasting becomes more reliable with the straight-line method.
  • This method is useful for businesses that have significant year-to-year fluctuations in production.
  • Straight line method is also convenient to use where no reliable estimate can be made regarding the pattern of economic benefits expected to be derived over an asset’s useful life.
  • Moreover, the Straight-Line Method ensures a steady impact on profits, avoiding the fluctuations that might arise from methods that front-load depreciation expenses.
  • Straight line basis, also called straight line depreciation, refers to a measure of determining depreciation and amortization on assets.

While the straight-line method of depreciation offers simplicity and consistency in your accounting practices, it’s important to understand its limitations to manage your business assets effectively. Other methods exist, but they require the company to estimate the trajectory of valuable service over time. Not to mention, many tax authorities favor the straight line method, making it a popular choice for straightforward bookkeeping. However, like any tool in your financial toolbox, it’s not always the most suitable for every situation or every asset.

Example of Straight Line Depreciation

Accumulated depreciation is a contra asset account, which means that it is paired with and reduces the fixed asset account. Accumulated depreciation is eliminated from the accounting records when a fixed asset is disposed of. Companies use the straight line basis method to determine the amount to be expensed over accounting periods. To calculate the depreciation of an asset, an asset’s salvage value is deducted from its purchase price the difference is then divided by the estimated useful years of the asset. The choice between these methods depends on a company’s financial strategy, cash flow needs, and tax planning objectives. For instance, a startup might prefer accelerated depreciation to minimize tax liabilities early on, while a mature company might opt for the straight-line method to smooth out expenses.

Middle Years Depreciation

Accelerated depreciation recognizes a higher loss of value in the earlier years of an asset’s lifespan, reflecting faster wear-and-tear or obsolescence upfront. This approach can be beneficial for businesses looking to maximize deductions sooner. In this lesson, I explain the basics of straight line method and how you can use it to calculate the depreciation expense. Additionally, the straight line basis method does not factor in the actual physical rapid loss of an asset’s value in the early years of its life. At the same time, it does not take into consideration the fact that an asset will likely require more maintenance as it ages. On the downside, the straight line basis method’s major pitfalls lie in its simplicity.

This can lead to errors on financial statements in which assets may appear more valuable than they truly are. The simplicity of this approach makes it easier to manage and maintain each financial statement, particularly if you have limited accounting tools and resources at your disposal. This expense reduces your net income, demonstrating how the depreciable asset contributes to your revenue generation over time. To calculate depreciation using a straight-line basis, simply divide the net price (purchase price less the salvage price) by the number of useful years of life the asset has. One of the most obvious pitfalls of using this method what is straight line method is that the useful life calculation is often based on guesswork.

Straight Line Depreciation Rate

Once you understand the asset’s worth, it’s time to calculate depreciation expense using the straight-line depreciation equation. The method can help you predict your expenses and determine when it’s time for a new investment and prepare for tax season. Learn how to calculate straight-line depreciation, when to use it, and what it looks like in the real world. The units of production method is based on an asset’s usage, activity, or units of goods produced.

You could assign the accounting calculations to a proverbial ham sandwich and expect a correct and useful result. The Motley Fool reaches millions of people every month through our premium investing solutions, free guidance and market analysis on Fool.com, top-rated podcasts, and non-profit The Motley Fool Foundation. It prevents bias in situations when the pattern of economic benefits from an asset is hard to estimate. Yes, but you’ll need IRS approval for the change and must update your accounting records accordingly. Next, you’ll estimate the cost of the salvage value by considering how much the product will be worth at the end of its useful life span. Now that you know what straight-line depreciation is and why it’s important, let’s look at how to calculate it.

In the competitive landscape of modern business, the strategic allocation of resources towards… In the realm of productivity, the concept of time management has evolved beyond mere scheduling and… Accumulated depreciation on 30 June 2020 will therefore be $2000 x 2.5 which is equal to $5000. Speaking of predictability, your financial forecasting becomes more reliable with the straight-line method. CFI is the global institution behind the financial modeling and valuation analyst FMVA® Designation.

The straight-line depreciation method makes it easy for you to calculate the expense of any fixed asset in your business. The straight line method charges the same amount of depreciation in every accounting period that falls within an asset’s useful life. The Straight-Line Method of depreciation spreads an asset’s cost evenly over its estimated useful life. Each year, the same amount of depreciation expense is charged to the income statement.

When it comes to depreciation methods, businesses are often faced with a choice between the straight-line method and accelerated depreciation methods. On the other hand, accelerated methods, such as the double-declining balance and sum-of-the-years’-digits, allow for greater depreciation expenses in the early years of an asset’s life. This choice can significantly impact a company’s financial statements and tax liabilities. It means that the asset will be depreciated faster than with the straight line method. The double-declining balance method results in higher depreciation expenses in the beginning of an asset’s life and lower depreciation expenses later. This method is used with assets that quickly lose value early in their useful life.

The amount of depreciation expense decreases in each year of an asset’s useful life under the straight line method. Using this amount, we can calculate the depreciation expense, accumulated depreciation, and carrying value of the asset for each year as follows. In case you’re confused at any step, read the explanation below the depreciation schedule.

6 Best Online Bookkeeping Services for Small Businesses in 2025

small business bookkeeping

A good setup ensures that every entry lines up with a specific business activity and gives structure to your financial reports. Small businesses also Bookkeeping for Consultants manage their own accounts receivable to make sure they get paid on time for goods and services that have already been bought or rendered. The process involves sending estimates and invoices and keeping track of due dates. Some accounting software comes with invoicing features, like automated payment reminders, or you may opt for separate invoicing software. Bookkeeping is the process of recording all your business’s financial transactions systematically.

Choose your bookkeeping method

small business bookkeeping

This practice simplifies tax preparation, protects personal assets, and can help you secure funding from creditors or bookkeeping investors. While some business structures, like sole proprietorships and some LLCs, may not legally require a separate bank account, it is highly recommended. Start with a business checking account and consider adding a business savings account to organize funds for various purposes, including tax planning. FreshBooks offers a straightforward approach to managing finances, making it exceptionally accessible for beginners and established businesses alike.

  • Let’s use the cash flow coverage ratio as an example, which will tell you if you have enough cash to pay off debts in the short term and the long term.
  • A larger company that also manages accounts payable and accounts receivable, or requires advanced financial reports, might need 5 to 10 hours per week.
  • The platform’s commitment to consistency across devices ensures that as businesses grow, their accounting access remains unhindered, whether they’re at the office desk or on the move.
  • QuickBooks is a good choice for freelancers and small businesses that need a simple way to track expenses, organize receipts and log mileage.

Who should manage small-business bookkeeping tasks?

ERP software is typically used by larger businesses while accounting software is unearned revenue more suited for small businesses. ZarMoney is a customizable software built for businesses that need flexibility and precision. At its core, it offers dynamic invoicing capabilities allowing businesses to generate bespoke online invoices tailored to their specific requirements.

small business bookkeeping

Maintaining cash flow & improved financial management

Most options cover basic invoices, expenses, and financial reports, but typically lack more advanced features like payroll, double-entry bookkeeping, or automated bank account sync. They might work well for a new business, but as your financial transactions increase, you may need to invest in more comprehensive accounting software or hire a bookkeeper. How often are you looking at your total current income and total current expenses?

small business bookkeeping

Advanced and industry-specific accounting features

small business bookkeeping

You can filter reports by date, customer, vendor, item and other fields. You can also customize the visual layout of your reports using graphs, charts and maps. Once I filled in the form using drop-down selections or by manually entering text into the field, I simply had to click “approve and email” to send it. Along the top of the interface is a menu with options such as “business,” “accounting,” “projects” and “contacts.” When you click a menu option, you are given a list of options. For example, when you click “projects,” you are given the option to go to your list of projects or a report of staff cost rates.

small business bookkeeping

9 Best Free️ Google Sheets Nonprofit Budget Templates for 2023

sample nonprofit budget

A benchmark is 80%, but it’s not a hard and fast rule, and depends on your organizational needs. It’s important to keep in mind the difference between fixed and variable costs when you are tracking expenses. These expenses include salaries for administrative, support, and fundraising staff. Also included in this section might be rent, utilities, and technology for office space, and legal and other miscellaneous expenses. As such, nonprofit employees are the third-largest workforce among the US industries, following after the retail and food industries. As you walk through your event list, add the amounts you’ll need to make each one happen.

sample nonprofit budget

General and Administrative Expenses

Make sure you include space for corporate donations on your budget, so you get a clear idea of how your income is split between individuals and corporations. This will help you plan your activities for the year ahead, so you know who to target with your campaigns and marketing. Having a budget will also make you look super organized and efficient. With a proper budget set you can concentrate on discussing items that matter and making the big decisions, because you don’t need to spend time worrying about your cash flow. Make sure your budget clearly outlines the key components needed to sustain operations, so all stakeholders understand how financial resources are being managed. This is especially important for nonprofits that rely heavily on grants or fundraising events, which often lead to large, accounting services for nonprofit organizations irregular payments instead of a steady revenue stream.

Startup Operating Budget

sample nonprofit budget

A well-crafted narrative is a powerful tool for securing funding and demonstrating the value and impact of government programs. A sample of budget narrative provides a roadmap for successfully navigating this critical process. When creating a nonprofit organization budget template, consider common budgeting categories your expenses may fall under. This gives you a greater understanding of the different business aspects of a nonprofit and provides a framework for considering how to most effectively distribute your funds. Candid’s budget templates have proven useful for organizations of all sizes.

  • TechSoup provides free budget templates and planning resources as part of their nonprofit technology and capacity building mission.
  • It contains two budgets for different fiscal periods that can be compared to each other like–for–like as you work your way through to the end of the current fiscal year.
  • They must submit their financial statements that include the salaries of directors, key employee sheets, etc.
  • Their on-the-ground perspective will help forecast realistic program costs and identify cost-saving opportunities.
  • Through this, nonprofit gets a budget that it can spend for all its programs or projects.

Document And Share

Below we discuss the mistakes that companies or organizations make with their solution. Alongside your water and energy costs, you’ll also need to think about your phone and internet provisions. Record them here and take the opportunity to compare them against what’s available on the market.

Free Debt Payment Schedule Templates – Excel, PDF

Take advantage of conditional formatting to set a rule where a minus figure turns the cell red. If you’re running events or have a new program coming up, you’ll probably need to print materials to let people know all about it. Group your print and postage costs together here, so you can get a feel for how much you’re spending on sending out materials to your audience. You might realize you could switch to an online program, or swap your thank you letters for personalized thank you videos instead.

Global Giving Nonprofit Budget Template

sample nonprofit budget

The nonprofit sample budget helps you to create a perfect plan to manage the income and expenditure of the organization. Unlike simple sample nonprofit budget templates, this toolkit emphasizes understanding the why behind budgeting decisions. It promotes a strategic approach to financial planning, aligning budget development with the organization’s mission and program goals.

What to include in your nonprofit budget template

A Government Agency Program Budget Narrative is essential for all publicly funded programs. It serves as a key component of the budget justification process, providing transparency and accountability to taxpayers and legislative bodies. A strong narrative demonstrates the agency’s commitment to responsible resource management and builds public trust. It’s not just about getting the numbers right; it’s about telling the story of how those numbers translate into positive outcomes for the public.

Spotlight: The Austin Diaper Bank

sample nonprofit budget

Another method for tracking your budget is to track and project cash flow for the year. The best way to do this is to track cash inflow–revenues and donations–and cash outflow–expenses. This helps you better understand when https://greatercollinwood.org/main-benefits-of-accounting-services-for-nonprofit-organizations/ you have revenue coming in and expenses going out, on a monthly and yearly basis.

sample nonprofit budget

How to create a budget for a nonprofit organization

Clarify who will oversee different aspects of the budget as your project takes shape and outline the processes that will guide them. At this stage, it’s also important to assign roles to those involved in budget management. This budget allocates funds for unplanned or emerging opportunities, such as piloting a new program, investing in innovative technologies, or responding to unexpected needs. A capital budget focuses on long-term investments and major expenses, such as acquiring property and equipment, or technology upgrades. However, the budget type you choose will depend on the size of your nonprofit and where you are in your mission’s journey.

What is CIP Accounting And How to record CIP in Accounting

what is cip accounting

CIP represents capital investment in assets under construction, expected to provide future economic benefits. During construction, CIP is not depreciated because it’s not yet available for use. All direct project costs are accumulated in the CIP account and transferred to the appropriate fixed asset account upon completion, where depreciation begins.

what is cip accounting

Additional Costs

CIP accounting is a powerful tool for organizations to measure financial performance, track project costs, and make informed decisions. By understanding the key principles, benefits, and limitations of CIP accounting, organizations can unlock its full potential and gain a competitive edge in the market. Whether in construction, manufacturing, or IT, CIP accounting is an essential tool for businesses seeking to improve their financial performance and drive growth.

Challenges in Construction-in-Progress Accounting

  • The article is to help you have a clear understanding of how to do accounting treatment of construction in progress in financial statements of a business.
  • By capitalizing costs that are still in progress, businesses can avoid misrepresenting their financial statements by inflating expenses or understating the value of their projects.
  • In addition, the new asset’s balance matches the CIP balance plus any additional financing and closing costs attached to the permanent financing.
  • This system not only facilitates more accurate reporting but also aids in identifying cost overruns and inefficiencies early in the project lifecycle.
  • Build to use can be an extension in an existing office facility, building a new plant, warehouse, or any business asset.
  • This collaborative approach helps in identifying and addressing problems early, thereby reducing the risk of delays and cost overruns.
  • Among them, learning how to record construction in progress accounting stands out.

Accurate financial records are essential for construction companies to track project costs, stay within budget, and provide clarity for stakeholders. Construction projects require a specialized approach known as Construction in Progress (CIP) accounting. This method allows companies to manage expenses for ongoing projects, keeping finances organized until completion. In this guide we’ll explore CIP accounting in construction, its representation on the balance sheet, and how Planyard can streamline the process. CIP accounts reflect capital investments and appear as fixed assets, while WIP costs are reported under inventory on the law firm chart of accounts balance sheet.

Everything You Need To Know About Construction In Progress (CIP) Accounting

In volatile economic climates, this foresight is invaluable for maintaining agility and adaptability. The CIP account usually contains information for multiple fixed assets under construction. The CIP account, therefore, accumulates costs for a fixed asset until it is ready for use.

  • Properly managing CIP on the balance sheet ensures accurate reporting of an organization’s financial position and prevents misstatements that could affect decision-making.
  • Detailed documentation—receipts, invoices, records—is crucial for accuracy and audit readiness.
  • This information is crucial for management to make informed decisions about resource allocation and project continuation.
  • Construction work-in-progress accounting refers to the record-keeping of all expenditures that accrue in constructing a non-current asset.
  • Laura has worked in a wide variety of industries throughout her working life, including retail sales, logistics, merchandising, food service quick-serve and casual dining, janitorial, and more.
  • GAAP allows another method of revenue recognition for long-term construction contracts, the percentage-of-completion method.

Step 1: Identify CIP Expenses

Once the project is completed, transfer the total CIP balance to the appropriate fixed asset account. The CIP procedures dictate the proper recording of construction costs in financial statements. In the company’s balance sheet, construction in progress is most commonly found under the head of PP & E( Plant, Property & Equipment). Statutory accounts, often referred to as financial statements, provide stakeholders with a comprehensive view of a company’s financial performance and position.

what is cip accounting

What Is Included in the Construction in Progress Balance?

what is cip accounting

This gives you a firsthand look at how we can support your financial goals and enhance your business operations. The basis for the effort expended can be labor hours, the material used, cip accounting or machine hours. However, there are chances that the term process written in a financial statement instead of progress indicates the business nature.

what is cip accounting

Understanding Direct Costs in Financial Management

what is cip accounting

Once expenses are recorded, they need to be allocated to the appropriate asset account. online bookkeeping Upon project completion, the company transfers the CIP balance to the “Buildings” fixed asset account, and depreciation begins. Some countries or tax jurisdictions may allow businesses to claim tax deductions or benefits related to the costs incurred during the construction or development phase. By capitalizing these costs, companies can more accurately calculate and support their tax deductions, ensuring compliance with applicable tax laws.

Paycheck Calculator: Calculate Federal, State & Local Taxes

salary paycheck calculator

The federal supplemental tax rate is currently 22% for bonuses over $1 million and 37% for supplemental wages of over $1 million. Paycards are prepaid debit cards onto which employers load an employee’s pay. The Federal Income Tax is collected by the government and is consistent across all U.S. regions. In contrast, the State Income Tax is levied by the state of residence and work, leading to substantial variations. The Social Security Tax is used to fund Social Security, which benefits retirees, persons with disabilities and survivors of deceased workers. Medicare involves a federal payroll tax designated for the Medicare insurance program.

  • Therefore, only federal income taxes and FICA taxes (6.2% for Social Security and 1.45% for Medicare) will be deducted from your paycheck.
  • Some deductions are “post-tax”, like Roth 401(k), and are deducted after being taxed.
  • With Compensation Planning Software, you can simplify compensation calculations, including retroactive pay.
  • Reading them is simply a matter of making sure the payment information is correct.
  • Unlike withholding certificates and other employment documents, paychecks are pretty easy to decipher.
  • However, some states still have exemptions in their income tax calculation.

Exempt

With Compensation Planning Software, you can simplify compensation calculations, including retroactive pay. This helps prevent errors and improves accuracy in your compensation planning. However, the more practical figure for daily budgeting is your after-tax income (also known as net income or disposable income). This is the amount that actually lands in your bank account after all taxes and deductions, and it reflects what you can use to pay rent, bills, and other expenses.

Do you get taxed more if paid monthly versus biweekly?

salary paycheck calculator

Understanding how these factors affect your take-home pay can help you budget more effectively and plan for the future. Use our Take-Home Pay Calculator to estimate your after-tax income and take control of your finances today. PaycheckCity has been offering precise salary calculations to countless individuals, small enterprises, and payroll experts annually.

Retirement Contributions

Pre-tax deductions are amounts taken out of your gross pay before income taxes are calculated. These might include contributions to retirement plans, health insurance premiums, or Health Savings Accounts. For each payroll, federal income tax is calculated based on wages and the answers provided on the W-4 and year to date income, which is then referenced to the tax tables in IRS Publication 15-T. Again, the percentage chosen is based on the paycheck amount and your W4 answers. While there isn’t any one size that fits all when it comes to your tax withholdings, generally you can expect to have both FICA and federal income taxes withheld from your pay. When it comes to tax withholdings, employees face a trade-off between bigger paychecks and a smaller tax bill.

Benefit deductions refer to the amounts withheld from an employee’s paycheck to provide employees with access to various benefits and insurance programs offered by their employer. Both employees and employers pay 1.45% for Medicare and 6.2% for Social Security. The latter has a wage base limit of $176,100, which means that after employees earn that much, the tax is no longer deducted from their earnings for the rest of the year. Those with high income may also be subject to Additional Medicare tax, which is 0.9%, paid for only by the employee, not the employer. Learning to calculate retroactive pay is critical for making sure employees receive the correct compensation for wage adjustments.

Step 6 – Your paycheck

It’s important for employees to keep track of their accrued leave days, and for employers to manage them properly. Understanding the company’s policies regarding accrued leave will help ensure that employees receive the time off they’re entitled to and that employers avoid any confusion or disputes. Residents and citizens are taxed on worldwide income (working overseas, etc.). In contrast, nonresidents are taxed only on income salary paycheck calculator within the jurisdiction. If you work for yourself, you need to pay the self-employment tax, which is equal to both the employee and employer portions of the FICA taxes (15.3% total).

Input your general information, federal and state information (including filing status and allowances), and any voluntary deductions (such as retirement contributions or health insurance premiums). Salaried employees should enter annual salary or earnings per pay period. Employers withhold federal income tax from their workers’ pay based on current tax rates and Form W-4, Employee Withholding Certificates. Subtract your gross income with income taxes (federal, state, local) and payroll taxes (FICA, state insurance). You might need to minus deductions (401k, dental, etc) and additional withholdings.

  • Again, the percentage chosen is based on the paycheck amount and your W4 answers.
  • The most common delivery schedules are bi-weekly and semi-monthly, though this varies based on employer preferences and applicable state laws and regulations.
  • Gross pay is your total earnings before any deductions such as taxes, insurance premiums, or retirement contributions are taken out.
  • When you receive a paycheck, you’ll notice that the amount you get to take home is smaller than your gross salary.
  • Our salary paycheck calculator helps you determine your take home pay after taxes and benefit deductions have been subtracted.
  • The course of action depends on the reason for the missed or late paycheck.
  • Our take home pay calculator will then do the rest, calculating your salary and showing you you what you will receive after taxes and deductions.

It’s important to note that while past versions of the W-4 allowed you to claim allowances, the current version doesn’t. Additionally, it removes the option to claim personal and/or dependency exemptions. Instead, filers are required to enter annual dollar amounts for things such as total annual taxable wages, non-wage income and itemized and other deductions.

Different factors impact your net pay, such as your tax filing status, the number of dependents, federal and state income taxes withheld, as well as Social Security and Medicare taxes. Various deductions, such as for retirement, health insurance and a flexible spending account (FSAs) will also reduce your net pay. The calculator then applies relevant tax rates, deductions, and contributions to compute your net pay.

This transparency enables you to plan, budget, and manage your financial health more effectively. Remember, knowledge is power, especially when it comes to your hard-earned money. To calculate daily pay, divide your annual salary by the number of working days in the year (typically 260 for a standard 5-day work week). For hourly employees, it’s as simple as multiplying the number of hours worked in a day by the hourly rate.

Five Star Tax Services – IRS Tax Relief Specialists

A pay stub and a paycheck usually go hand in hand, but they serve different purposes. Employers and employees both pay 1.45% for Medicare and 6.2% for Social Security. When an employee starts a new job, they must fill out a W-4 form, a.k.a., the Employee’s Withholding Certificate.

To calculate your federal withholding by hand see these step-by-step instructions and examples. Social Security is also known as OASDI (Old Age, Survivors, and Disability Insurance). Employees can log into to verify their wages and confirm their benefits at various retirement ages. As your financial situation evolves, such as changes in salary, tax status, or deductions, update the calculator inputs to maintain accuracy in your paycheck estimations.

Nonprofit Financial Statements: Complete Guide with Examples

profit and loss statement for nonprofit organization

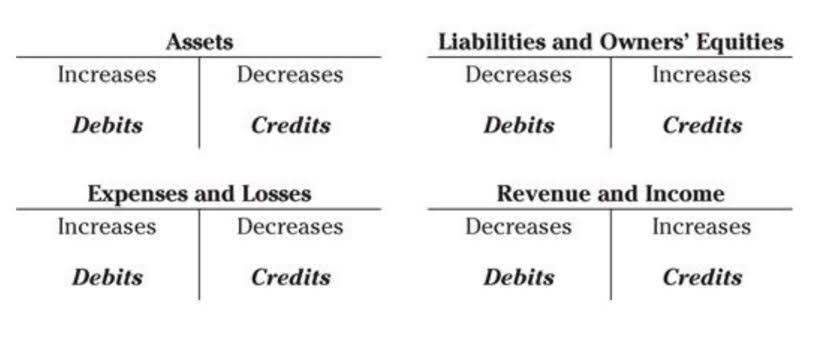
A listing of the accounts available in the accounting system in which to record entries. The chart of accounts consists of balance sheet accounts (assets, liabilities, stockholders’ equity) and income statement accounts (revenues, expenses, gains, losses). The chart of accounts can be expanded and tailored to reflect the operations of the company. The balance sheet reports the assets, liabilities, and owner’s (stockholders’) equity at a specific point in time, such as December 31. The balance sheet is also referred to as the Statement of Financial Position.

  • Beyond helping your organization meet legal requirements, they also promote transparency and help you evaluate your performance.
  • While the goal of a nonprofit organization is not to earn a profit, these organizations do make money.
  • This calculation shows the equity of your nonprofit organization and whether you have the revenue to cover expenses, creating a sustainable organization.
  • More than just documents for compliance, thoughtfully crafted financial statements are essential for transparency, strategic planning, and funding efforts.
  • You’ll need to record information about your organization’s expenses and revenue on your tax forms.
  • This document is a requirement for annual audits and categorizes your nonprofit’s costs based on their function according to your mission.
  • This part covers cash from your everyday activities, like running your programs and services.

Net assets:

profit and loss statement for nonprofit organization

Templates allow customization to capture metrics most relevant to the organization’s mission and operations. The clarity of routine reporting using Nonprofit Financial Statement Templates assists board governance and aids in securing donor funding through transparency. Nonprofit Financial Statement Templates provide a standardized structure for reporting key financial metrics that nonprofit organizations require for oversight, planning, and grant applications. Maintaining well-organized Nonprofit Financial Statement Templates ensures consistent bookkeeping and simplified reporting.

  • Nonprofits have essentially parallel reports, but because their accounting is different, the reports differ slightly as well.
  • Unlike for-profit businesses, these statements focus more on how money is used to achieve the organization’s goals.
  • For nonprofits that operate membership models, such as clubs, associations, or societies, membership dues are a primary revenue stream.
  • You should consider our materials to be an introduction to selected accounting and bookkeeping topics (with complexities likely omitted).
  • Second, it aids in budgeting and forecasting by revealing spending patterns and revenue trends.

Best Practices for Streamlining Your Endowment Management

  • While a traditional income statement exists to show a profit, or Net Income, a statement of activities exists to show the change in net assets.
  • Therefore, you need to make sure that your accounting system is well organized from start to finish, or else you may have errors in your statement.
  • For example, a company will have a Cash account in which every transaction involving cash is recorded.
  • Plus, this publicly available information can provide current and prospective donors with the context they need to decide whether they’d like to support your nonprofit based on how it employs its funds.
  • This statement shows how changes in the balance sheet and income statement affect cash and cash equivalents.
  • This includes everything from cash inflows and outflows related to fundraising events to payments on long-term investments like buildings.

Understanding this terminology can help stakeholders better engage with the organization’s financial reporting. While the statement of activities gives an overall view of financial performance by showing total expenses from total revenue, the statement of functional expenses breaks those numbers down. It details how much is spent on specific areas like programs, administration, and fundraising. This detailed breakdown allows you to see exactly where the money goes, making it easier to record revenue and expenses in a way that shows the true cost of achieving the nonprofit’s mission. Together, these statements help paint a clearer picture of how resources are used. Net assets in the statement of activities are like the fuel gauge in a car.

Financial Statements of Nonprofits

Or help you understand why your cash increased even as you lost money that quarter (maybe you dipped into your line of credit to make payroll). The Statement of Cash flows is a relatively simple report that shows if your cash has increased or decreased across 3 segments of your business. The Statement of Financial Position is a snapshot of what your organization owns and what it owes to others at a specific point in time. By consistently monitoring your cash inflows and outflows, you’ll be able to notice important trends and use them to adjust your financial strategy in the accounting services for nonprofit organizations future.

profit and loss statement for nonprofit organization

How to prepare financial statement for non-profit organization?

profit and loss statement for nonprofit organization

The income statement reports the revenues, gains, expenses, losses, net income and other totals for the period of time shown in the heading of the statement. If a company’s stock is publicly traded, earnings per share must appear on the face of the income statement. Many nonprofits publish their profit and loss statements on their websites in the “About Us” or “Financials” section.

profit and loss statement for nonprofit organization

Now you know the basics of the five essential financial reports that every nonprofit needs. On your Form 990, the IRS requires you to report your financial information according to different rules than you use for your audited financial statements. Even though you don’t have to pay federal taxes, almost all nonprofit organizations (the few https://nerdbot.com/2025/06/10/the-key-benefits-of-accounting-services-for-nonprofit-organizations/ exceptions are listed here) must file an IRS Form 990 each year. It’s probably the most practical financial statement a nonprofit Executive Director or CEO has for making intelligent decisions for their organization. If you or your board come from the for-profit world, it’s okay to call it a Balance Sheet among your team.

If you haven’t seen one for your organization yet or want to try your hand at compiling one, use our template to get started. Generally, nonprofits try to limit their operating expenses as much as possible to lower their overhead. It’s important to find the balance between reducing overhead to fund your mission and ensuring you dedicate enough funding to your operating activities to continue growing and expanding your organization. The expenses your organization incurs should all support your mission in some way, whether that’s by funding daily nonprofit operations or a specific project relevant to your mission’s purpose. Also included in your restricted revenue is temporarily restricted revenue. After that time elapses, they can be released from restriction and used as the nonprofit sees fit.

Payroll Checklist template Free template download

payroll processing checklist

Use our comprehensive, 13-step payroll checklist to ensure every stage is accounted for, whether you’re running payroll for the first time or auditing existing processes. In this article, we’ll guide you through the steps of payroll management — from preparation to post-processing audits. And, if you’re looking for a comprehensive payroll checklist to keep handy, we’ll provide one of those (for free), too.

Monthly bookkeeping made easy: Follow this checklist (with template)

So, to ensure that you create a streamlined payroll management process, creating a checklist becomes important. A payroll checklist is a list of activities that you need to perform to complete your payroll processing from end to end. Whether you are a seasoned payroll professional or new to payroll, a checklist can greatly help you. Before you start the payroll processing, ensure that you have all the accurate data of the employees in case of any inconsistency. When you pay employees, you should also allocate the money you’ve withheld from their checks to the proper accounts in your ledger. Chances are you remit your taxes quarterly, not every pay cycle, so you should store your payroll tax withholdings in your tax account until then.

Calculate employee net wages.

  • The minimum need is knowledge of payroll administration and familiarity with the different rules and taxes that apply.
  • To enhance security of TechRepublic we are requiring users to complete a one-time email verification before making any purchases.
  • Intuit does not endorse or approve these products and services, or the opinions of these corporations or organizations or individuals.
  • Before you cut paper checks or enter amounts for direct deposit, be sure to do a final pass to look for discrepancies and ensure you’re working with updated records.
  • Send confirmation to your client that the period’s payroll has been processed.
  • After calculating each employee’s net pay and making the necessary withholdings, these funds typically go into withholding accounts.

However, by following a checklist, you can reliably process payment using a payment form to meet the requirements of the state, industry, and the company’s employees. It is critical for users not to overlook any essential components of the payroll checklist to avoid drastic changes affecting their operations. Therefore, whether you choose to automate your payroll system or continue with manual processing, utilizing a payroll checklist provides many benefits that can help keep your team on schedule. We will also break down how Factorial’s software can help you build a compliant and efficient payroll system so that your business runs smoothly and you pay your employees accurately and on time. Ascertain that the bookkeeper or CPA is knowledgeable about all of the services you require and has the flexibility to adapt last-minute modifications to avoid processing errors.

Payroll Software, the Payroll Pro’s Perfect Sidekick

In some cases, we earn commissions when sales are made through our referrals. These financial relationships support our content but do not dictate our recommendations. Our editorial team independently evaluates products based on thousands of hours of research.

Payroll Checklist For Your Business Download Free Templates

  • It could also mean checking whether wage garnishments are necessary, if home addresses have changed and if salaries have been raised.
  • Payroll is part and parcel of being an employer, and a payroll checklist can make the job easier.
  • In most cases, non-exempt (as opposed to exempt) includes hourly employees.
  • In payroll and accounting, being able to “tie out” as you go is very important.
  • Managing payroll is a complex yet crucial aspect of running a successful business.
  • Payroll processing is a detailed process that requires various tasks to ensure that paychecks are processed accurately, and payroll tax and benefits compliance is met.
  • Whether you’re looking to collect customer information, order type and quantity; our forms can be customized to fit your needs.

Hiring a payroll services business is another option to ensure the correctness of your payroll system. These companies take care of your company’s real payroll needs, including monthly salary receipts, deposits, and deductions. These payroll service providers frequently guarantee complete accuracy payroll processing checklist and avoid late payments.

payroll processing checklist

Verify Employment and Complete Tax Forms

Your entire team will rely on the data you’ve gathered to carry out their operations. These personnel, ranging from branch managers to department heads, may use the information included in your payroll records to make critical decisions for their respective teams. Maintaining a copy of these records is also necessary for tax payments, financial document processing, and budgeting at the end of each year. Payroll administration is arguably one of the most challenging aspects of being an employer.

How to process payroll within your organization

Make sure you collect all the payroll information you need from each of your employees. Keep employment tax paperwork (such as Forms W-4) for at least four years. Payroll records must be kept for at least three years, according to the FLSA (e.g., wages paid, benefits, etc.). Also, save salary computation records (such as time cards, work schedules, and so on) for at least two years. Employee payroll paperwork can be stored electronically on your computer, smartphone, or tablet or by utilizing payroll or HR software.

The Payroll Checklist: A Step-by-Step Guide for Running Payroll

payroll processing checklist

If you pay employees hourly or daily, you must also evaluate what constitutes overtime to be informed of their rights. Additionally, employees are responsible for time cards or timesheets to guarantee adequate compensation after each pay period. That means that this paperwork must be accurate, approved, and submitted on time; otherwise, compensating an employee will be extremely difficult. Pratiiek Mavani is a seasoned professional in accountancy, taxation, audit, and finance, boasting over 16 years of industry expertise. He specializes in conducting audits for diverse entities including banks, optimizing their core processes through cost management and budgeting.

Gather employee information

payroll processing checklist

An IT Service Ticket Form is a form template designed to streamline IT service management within organizations. A Free Client Consultation form template is designed to streamline the process of collecting client information and scheduling appointments for consultants and small business owners. Outsource your payroll services using Gusto, or adjust to suit your own system and requirements. But as your client base grows, payroll can quickly become one of the most procedure-bound, time-intensive tasks in accounting. Streamlining your payroll processes will help you attain that freedom. This is the end of our discussion on the payroll process checklist.

Distribute tax withholdings

This way, if any discrepancies arise, you can easily trace back to the point of origination. At the end of the payroll process, you’ll have department leaders, managers, vendors, and others who rely on the data you just compiled. Once you’ve done a final review of the completed payroll, you want to make sure appropriate people get the information they need. Payroll is often the largest budget item for your company, and it’s important you’re following through and providing reports key stakeholders need. Making tax payments according to the required payment schedule is vitally important once payroll has been completed.

Gather and consult up-to-date employee data and compliance requirements

  • This guide and the accompanying spreadsheet, created by Erik Eckel for TechRepublic Premium, will help you get things right.
  • This template outlines steps for running payroll on Gusto but is designed to be versatile, allowing customization to fit your specific systems and needs.
  • It’s part of operating your business legally—according to state laws and the Fair Labor Standards Act (FLSA).
  • So, to ensure that you create a streamlined payroll management process, creating a checklist becomes important.
  • Please enter the information, and these digital platforms will capture and retain it.
  • Monitor construction workers with this free, online evaluation form.

Next, you’ll want to calculate gross pay, or the total pay earned before taxes and deductions. This is also the time to check on PTO, additional pay such as commissions and bonuses, and any other factors that will influence your employees’ paychecks. Payroll software can automate many things, but you still must address some items, such as verifying employee information.

A Women’s Comp Order Form Template is a form template designed to streamline the process of collecting orders for uniform, jersey, and clothing sellers. Here are a few templates for different types of payroll implementation checklists. You can customize these templates for your business per your needs. Review your employee information prior to running payroll to ensure everything is up to date. All timesheets should be current and contain accurate employee data, overtime, sick leave, and other special considerations.

  • Collecting payment online is incredibly simple using a Jotform payment form.
  • You’d normally calculate gross wages for salaried and hourly employees.
  • Automated payroll and time-tracking tools can reduce the time to process payroll.
  • In order to capture the total amount due, this form template uses the Form Calculation widget.
  • You’ll then determine the net pay amount, pay your employees, and make tax deposits to the relevant tax agencies on time to comply with tax regulations.
  • With your identifying and tax payment information all set, you can now collect your employees’ tax information.

Online Interview Questionnaire Form

If you save the information digitally, keep backup copies in case your device or program fails. Additionally, keep your employee papers using secure software or a digital filing system. Check for changes in employee data – Check if there were any changes in the employee’s details, such as marital status, address, bank account number, etc. It’s almost time to officially run your payroll, so it’s time to submit it.

payroll processing checklist

The three stages of payroll processing are data collection, calculation, and disbursement. In the data collection stage, employers gather information such payroll processing checklist as employee details, hours worked, and any deductions or withholdings. This information helps with the calculation stage, where tax withholdings, overtime wages, and other variables determine the net payment amount. In the disbursement stage, you make payments to employees through methods such as direct deposit or paper checks.

Once you approve all your employee time cards, you’re ready to run payroll and issue payments. Approval is one of the most important steps when running payroll for employees. This is your chance to make sure all the hours add up and are correct so payroll is accurate. Once the total has been calculated, it’s time to add taxes and payroll deductions to one’s salary. Examine this data for inconsistencies to see whether you need to clarify a few points before going to the next phase.

Small Business Resources

You’ll also find out how to collect employees’ income and tax information and use this data to calculate paycheck amounts. Then, we’ll guide you through actually paying your employees once you know what you owe. You can never be assured when it comes to your payroll information, no matter how many times you review it. After all, you don’t want to send out paychecks riddled with errors because it would imply more revisions and complaints for you to deal with.

Leverage Payroll Software for Efficiency

Every company is aware of the difficulties inherent in creating a healthy work environment—which often include keeping employees happy and satisfied. You can provide your employees with all the facilities and equipment necessary to complete a task. Still, if you fail to compensate them for their efforts, you can expect their dissatisfaction to impair their performance. With the variety of payroll templates accessible, a payroll checklist is one of the few tools you can use to its full potential. Therefore, before you begin processing payroll, here are a few points to keep in mind to help streamline your system.