

CIP represents capital investment in assets under construction, expected to provide future economic benefits. During construction, CIP is not depreciated because it’s not yet available for use. All direct project costs are accumulated in the CIP account and transferred to the appropriate fixed asset account upon completion, where depreciation begins.
Additional Costs
CIP accounting is a powerful tool for organizations to measure financial performance, track project costs, and make informed decisions. By understanding the key principles, benefits, and limitations of CIP accounting, organizations can unlock its full potential and gain a competitive edge in the market. Whether in construction, manufacturing, or IT, CIP accounting is an essential tool for businesses seeking to improve their financial performance and drive growth.
Challenges in Construction-in-Progress Accounting
- The article is to help you have a clear understanding of how to do accounting treatment of construction in progress in financial statements of a business.
- By capitalizing costs that are still in progress, businesses can avoid misrepresenting their financial statements by inflating expenses or understating the value of their projects.
- In addition, the new asset’s balance matches the CIP balance plus any additional financing and closing costs attached to the permanent financing.
- This system not only facilitates more accurate reporting but also aids in identifying cost overruns and inefficiencies early in the project lifecycle.
- Build to use can be an extension in an existing office facility, building a new plant, warehouse, or any business asset.
- This collaborative approach helps in identifying and addressing problems early, thereby reducing the risk of delays and cost overruns.
- Among them, learning how to record construction in progress accounting stands out.
Accurate financial records are essential for construction companies to track project costs, stay within budget, and provide clarity for stakeholders. Construction projects require a specialized approach known as Construction in Progress (CIP) accounting. This method allows companies to manage expenses for ongoing projects, keeping finances organized until completion. In this guide we’ll explore CIP accounting in construction, its representation on the balance sheet, and how Planyard can streamline the process. CIP accounts reflect capital investments and appear as fixed assets, while WIP costs are reported under inventory on the law firm chart of accounts balance sheet.
Everything You Need To Know About Construction In Progress (CIP) Accounting
In volatile economic climates, this foresight is invaluable for maintaining agility and adaptability. The CIP account usually contains information for multiple fixed assets under construction. The CIP account, therefore, accumulates costs for a fixed asset until it is ready for use.
- Properly managing CIP on the balance sheet ensures accurate reporting of an organization’s financial position and prevents misstatements that could affect decision-making.
- Detailed documentation—receipts, invoices, records—is crucial for accuracy and audit readiness.
- This information is crucial for management to make informed decisions about resource allocation and project continuation.
- Construction work-in-progress accounting refers to the record-keeping of all expenditures that accrue in constructing a non-current asset.
- Laura has worked in a wide variety of industries throughout her working life, including retail sales, logistics, merchandising, food service quick-serve and casual dining, janitorial, and more.
- GAAP allows another method of revenue recognition for long-term construction contracts, the percentage-of-completion method.
Step 1: Identify CIP Expenses
Once the project is completed, transfer the total CIP balance to the appropriate fixed asset account. The CIP procedures dictate the proper recording of construction costs in financial statements. In the company’s balance sheet, construction in progress is most commonly found under the head of PP & E( Plant, Property & Equipment). Statutory accounts, often referred to as financial statements, provide stakeholders with a comprehensive view of a company’s financial performance and position.
What Is Included in the Construction in Progress Balance?
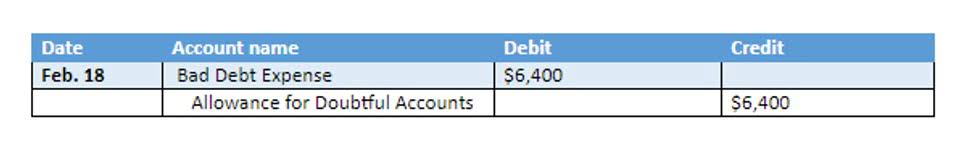
This gives you a firsthand look at how we can support your financial goals and enhance your business operations. The basis for the effort expended can be labor hours, the material used, cip accounting or machine hours. However, there are chances that the term process written in a financial statement instead of progress indicates the business nature.
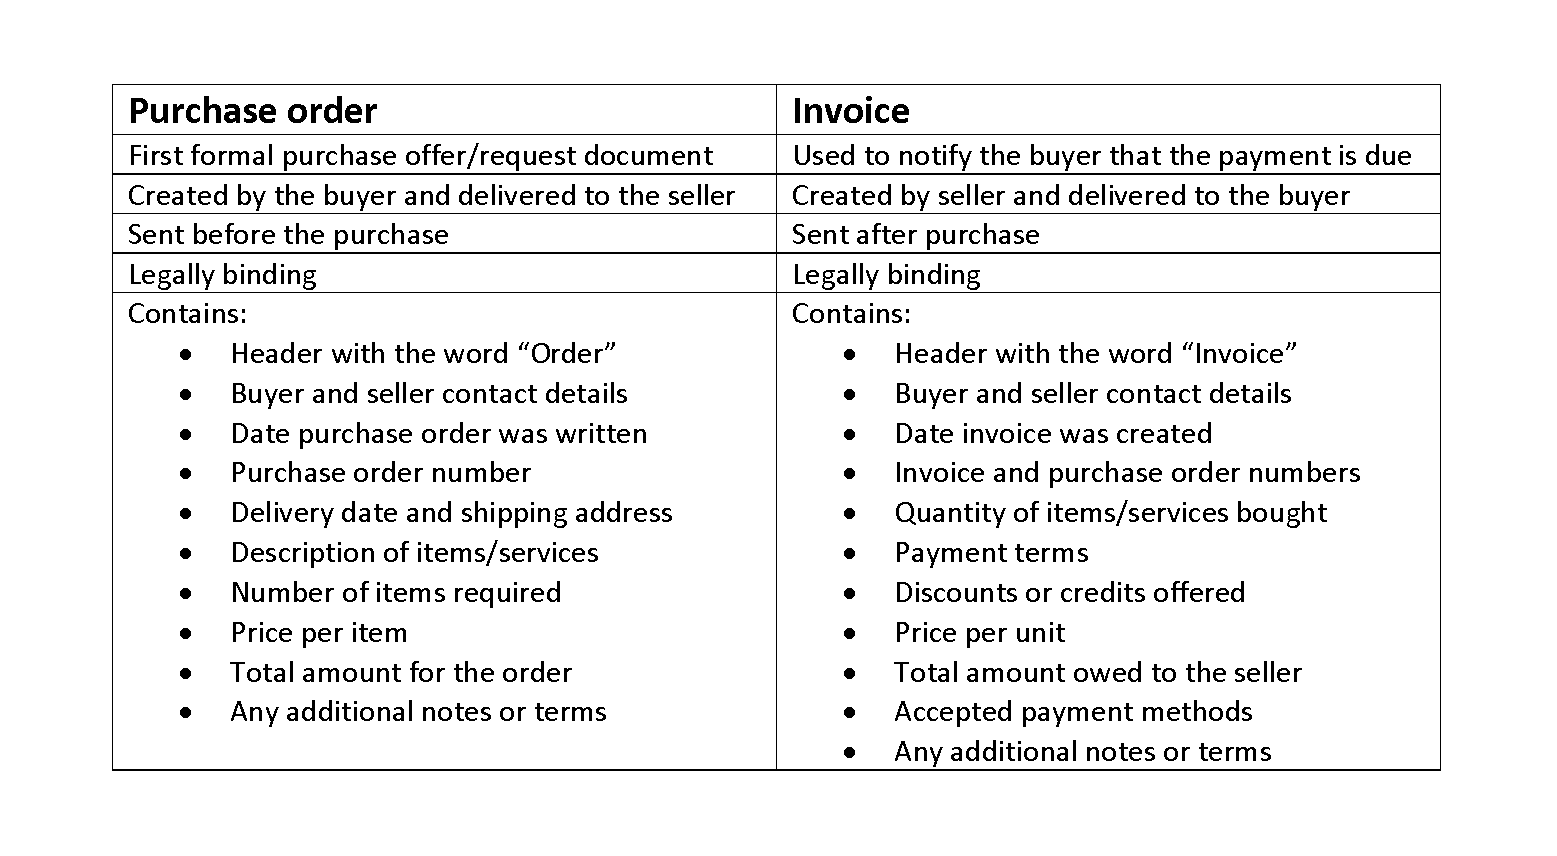
Understanding Direct Costs in Financial Management
Once expenses are recorded, they need to be allocated to the appropriate asset account. online bookkeeping Upon project completion, the company transfers the CIP balance to the “Buildings” fixed asset account, and depreciation begins. Some countries or tax jurisdictions may allow businesses to claim tax deductions or benefits related to the costs incurred during the construction or development phase. By capitalizing these costs, companies can more accurately calculate and support their tax deductions, ensuring compliance with applicable tax laws.